Does Homeowners Insurance Cover Foundation Repair in Texas?
By Quality Foundation and Plumbing · Published August 3, 2026
Texas homeowners insurance usually excludes foundation damage from soil movement, but there's a key exception when a plumbing leak is the cause. Here's how coverage actually works.
 Get My Free Estimate
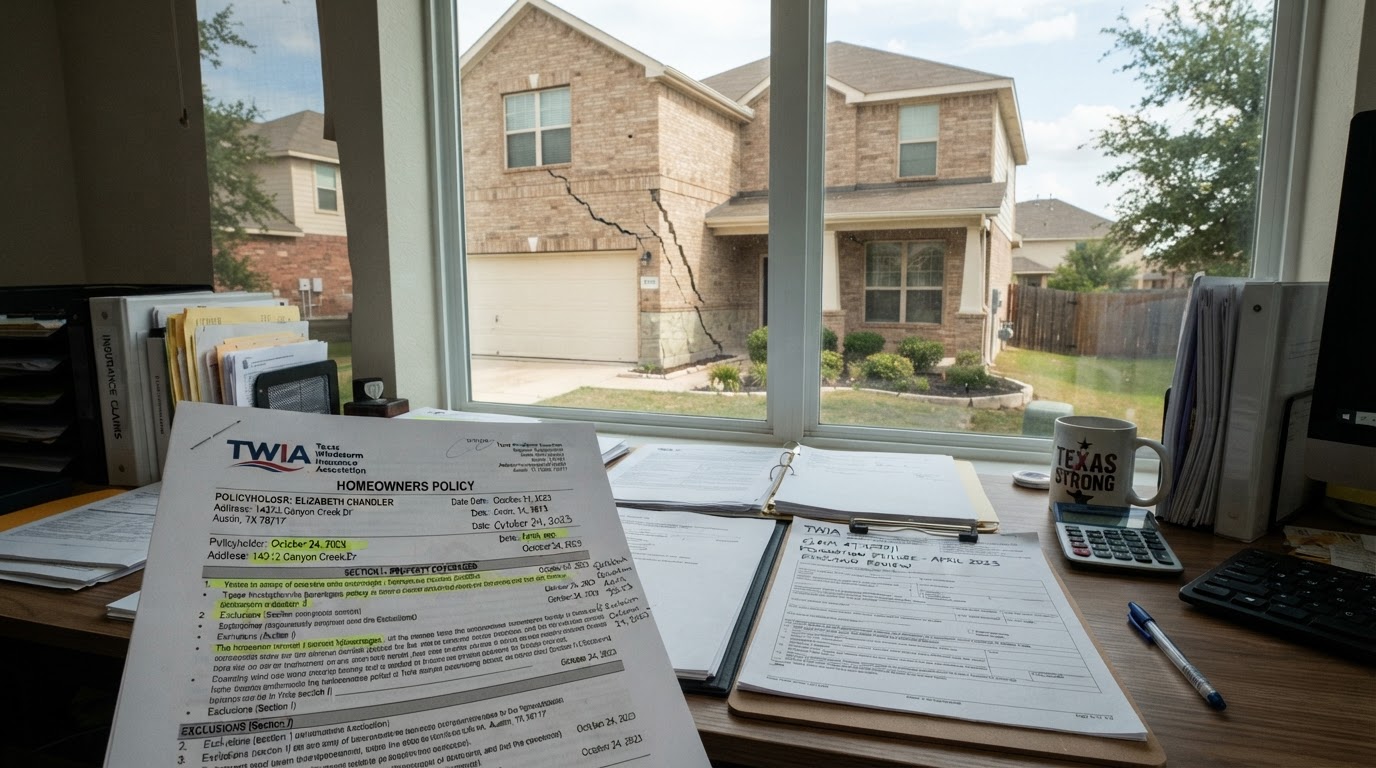
In most cases, no. Standard Texas homeowners insurance excludes foundation damage caused by soil movement, which is the most common cause of foundation problems in this state. The major exception is foundation damage caused by a sudden, accidental plumbing leak, which many policies do cover, at least in part.
That distinction, soil movement versus plumbing failure, is the single most important factor in whether a foundation claim gets paid. If you're wondering whether insurance covers foundation repair in Texas, here's how it actually works, and what to do if you suspect a leak is behind your foundation damage.
The Short Answer
A standard Texas homeowners policy (HO-A or HO-B form) will typically deny a foundation claim if the cause is expansive clay soil, drought, settling, or gradual erosion. It will typically consider covering the claim if the cause is a sudden, accidental event, most commonly a burst or ruptured pipe under the slab (Two Bros Foundation Repair, 2026; Perma Pier Foundation Repair of Texas).
Texas sits on some of the most reactive clay soil in the country, which swells when wet and shrinks when dry. Insurers classify that kind of gradual movement as a foreseeable, maintenance-related condition rather than an insurable accident, which is why it's excluded almost universally (The Agent's Office).
Why Standard Texas Policies Exclude Foundation Damage
The Earth Movement Exclusion
Nearly every homeowners policy sold in Texas contains an "earth movement" exclusion. The Texas Department of Insurance notes that standard homeowners forms exclude losses from earth movement, along with several other named perils, unless a specific endorsement is added back (Texas Department of Insurance, 2018). Policy language typically reads something like: the insurer does not cover loss caused directly or indirectly by earth movement, including earthquake, landslide, mudflow, or earth sinking, rising, or shifting, regardless of whether the movement was caused or made worse by weather conditions.
Because expansive soil movement is considered a form of earth movement, foundation cracking, heaving, or settling tied to clay soil, drought, or poor drainage generally falls under this exclusion, no matter how significant the resulting damage is.
Why Insurers Treat Foundation Movement as Preventable, Not Sudden
Insurance is built around the idea of insuring against sudden, unexpected losses, not gradual wear or conditions homeowners could have addressed through maintenance. Foundation movement from soil almost always develops slowly, over months or years, which puts it in the same excluded category as mold, rot, and general deterioration (TaxShark, foundation insurance overview). Insurers view this as a maintenance and construction issue, not an insurable risk.
The Key Exception: Plumbing Leaks
This is where things change. If a water supply line, drain line, or sewer line breaks suddenly beneath your slab and the resulting water causes soil erosion or foundation movement, many Texas homeowners policies will cover at least part of the resulting damage (NerdWallet, plumbing coverage guide; Progressive). This depends on your policy form: the basic HO-A form generally does not cover under-slab plumbing leaks or the resulting slab damage, while HO-B and HO-3 forms often do (Texas Watch).
What Counts as "Sudden and Accidental"
Insurers draw a hard line between a leak that happened quickly and one that developed over time. A pipe that bursts and floods the slab within hours or days is generally treated as a covered, sudden loss. A slow, undetected drip that went unnoticed for weeks or months is generally treated as gradual damage and excluded, even though the underlying event, a leaking pipe, is the same in both cases (Allied Public Adjusters, slab leak coverage).
This is why documentation and timing matter so much in a foundation claim tied to plumbing. Adjusters will often look for evidence of how long the leak had been present before it was discovered.
What's Typically Covered vs. Excluded
When a sudden plumbing leak is the documented cause, coverage often includes:
- Water damage to floors, walls, and personal property caused by the leak
- The cost to cut into and remove the section of slab needed to access the broken pipe
- Repairing the structure and flooring after the leak is fixed
Coverage typically does not include:
- The cost to repair or replace the plumbing pipe itself (plumbing wear and tear is generally excluded)
- Damage from a leak the insurer determines was slow, long-term, or the result of deferred maintenance
- Foundation movement the insurer attributes primarily to soil conditions rather than the leak, even if a leak was also present
Because of this split, foundation damage claims involving both a leak and pre-existing soil issues can be contested, and it's common for insurers and homeowners to disagree about the primary cause.
How to Find Out If a Plumbing Leak Caused Your Foundation Damage
Before filing a claim, it helps to establish whether plumbing is actually involved. Signs that point toward a plumbing-related cause include unexplained spikes in your water bill, warm spots on flooring above a hot water line, musty odors or damp carpet with no obvious source, and cracking that appears suddenly rather than gradually over seasons.
A licensed plumber can run a hydrostatic or leak-detection test to confirm whether water is escaping beneath the slab, and that documentation is often what an insurance adjuster needs to evaluate the claim. Foundation contractors can separately assess whether the pattern of movement is consistent with water intrusion versus broader soil movement across the whole slab.
Optional Coverage: Foundation and Water Damage Endorsements
Because standard policies exclude so much foundation-related risk, many Texas insurers offer optional endorsements that add back some coverage. These are sometimes called foundation endorsements, extended water damage coverage, or slab leak coverage, and they're commonly capped around 15% of your dwelling coverage limit. For example, up to roughly $45,000 on a $300,000 dwelling limit (Two Bros Foundation Repair, 2026 guide). Some carriers also sell separate foundation movement endorsements with lower limits, often in the $10,000 to $25,000 range, specifically for soil-related movement (The Agent's Office, HO-A/HO-B/HO-3 comparison).
If you live in an area with known expansive clay soil, much of North Texas, including Dallas, Frisco, and the surrounding Collin County communities, it's worth asking your agent directly whether these endorsements are available and what they cost, since they aren't included by default.
Filing a Foundation-Related Insurance Claim in Texas
Documentation That Helps
Insurance adjusters are more likely to approve a claim, or at least engage seriously with it, when a homeowner can show a clear, sudden cause. Useful documentation includes photos of visible damage as soon as it's noticed, a plumber's written report identifying the leak, its location, and an estimate of how long it had been active, water bill records showing a sudden increase, and a foundation inspection report describing the pattern of movement.
Insurers may send their own adjuster or engineer to inspect the property, and their conclusion about the cause of damage will often determine the outcome. Homeowners who disagree with a denial can request a re-inspection, hire an independent engineer, or file a complaint with the Texas Department of Insurance if they believe the claim was handled unfairly.
When to Call a Licensed Foundation and Plumbing Professional
Because coverage hinges on pinpointing the actual cause of foundation movement, an accurate diagnosis matters as much as the repair itself. A contractor who is licensed in both plumbing and foundation work can identify whether a leak is contributing to the damage, document findings in a way insurers recognize, and recommend the right repair once the cause is confirmed.
This article is general information, not insurance or legal advice. Policy language varies by carrier and endorsement, so the best next step for any specific claim is to review your policy with your agent or a licensed public adjuster.
Need Documentation for an Insurance Claim?
Quality Foundation and Plumbing serves Dallas and the surrounding North Texas area, holding General Contractor Registration #TL-GC-002004 and Master Plumber License MP-37229. If you suspect a plumbing leak is affecting your foundation, we can inspect and document findings that support your insurance claim.
Related: Slab Leak Detection & Repair | Foundation Repair | Can a Slab Leak Ruin Your Foundation? | DFW Foundation Repair Cost Guide
Sources cited in this post
- Two Bros Foundation Repair, "Foundation Repair Homeowners Insurance Coverage": https://www.twobrosfoundationrepair.com/research/foundation-repair-homeowners-insurance-coverage
- Perma Pier Foundation Repair of Texas, "Does Homeowners Insurance Cover Foundation Repair?": https://permapier.com/blog/does-homeowners-insurance-cover-foundation-repair/
- The Agent's Office, "Does Homeowners Insurance Cover Foundation Repair Texas?": https://theagentsoffice.com/does-homeowners-insurance-cover-foundation-repair-texas/
- Texas Department of Insurance, "Texas Homeowners Policies" (2018): https://www.tdi.texas.gov/reports/documents/texas-homeowners-policies-04122018.pdf
- TaxShark, "Does Homeowners Insurance Cover Foundation Issues?": https://taxsharkinc.com/does-homeowners-insurance-cover-foundation-issues/
- NerdWallet, "Does Homeowners Insurance Cover Plumbing?": https://www.nerdwallet.com/insurance/homeowners/learn/does-homeowners-insurance-cover-plumbing
- Progressive, "Does Insurance Cover Plumbing?": https://www.progressive.com/answers/does-insurance-cover-plumbing/
- Allied Public Adjusters, "Does Homeowners Insurance Cover Slab Leak Repairs?": https://alliedpa.com/resources/does-homeowners-insurance-cover-slab-leak-repairs/
- The Agent's Office, "HO-A, HO-B, HO-3 Policies: What's the Difference?": https://theagentsoffice.com/ho-a-ho-b-ho-3-policies-whats-the-difference-and-which-is-best-for-north-texas-homeowners/
- Texas Watch, "Overview of Texas Homeowners Policy Coverage": https://www.texaswatch.org/sites/default/files/Overview-of-Texas-Homeowners-Policy-Coverage1.pdf
Frequently Asked Questions
Does homeowners insurance cover foundation repair in Texas?
Usually not when the cause is soil movement, settling, or drought, because standard Texas policies exclude earth movement. Coverage is more likely when a sudden, accidental plumbing leak under the slab caused the damage, depending on your policy form and endorsements.
Does an HO-A policy cover slab leaks?
Generally no. The basic HO-A form does not cover plumbing leaks under the slab or the resulting foundation damage. HO-B and HO-3 forms often cover sudden leaks and the cost to access them, but not the pipe repair itself.
What documents help a foundation insurance claim?
Photos taken as soon as damage appears, a licensed plumber's leak detection report showing where the leak is and how long it was likely active, water bills showing the spike, and a foundation inspection report describing the pattern of movement.
What can I do if my foundation claim is denied?
You can ask for a re-inspection, hire an independent engineer or a licensed public adjuster, and file a complaint with the Texas Department of Insurance if you believe the claim was handled unfairly.